Hidden Costs of Manual Land Acquisition: How to Measure Them
Measure what manual land acquisition really costs: staff time, rework, delay and lost deals, parcel by parcel, using your own records.
Vignesh Nagarajan · · Updated · 9 min read · Source: Tamil Nadu Registration Department (TNREGINET)
On this page
- In short
- Start with a cost ledger, not a savings claim
- Define the unit and the clock before you count
- Count staff time from records, not assumptions
- Count rework only when an earlier step had to be repeated
- Separate real delay cost from exposure
- Call a price gap a variance, not an overpayment
- Record lost deals with a reason, and report only the spend as loss
- Run a 30-day baseline audit
- Test a platform claim with the same measurement
- What this means for you
- What this guide does not prove
- Test whether software pays back for your team
This guide is for operations and finance leads at land-buying teams. It shows how to cost a manual acquisition process from your own records. It does not give an industry average, which you should use only if the underlying dataset and comparison method are available, and it does not value any parcel.
In short
- Land, government charges, brokerage and agreed professional fees are visible costs. The hidden cost is process labour, repeated work, delay and fragmented coordination. Measure it separately; it is not a fixed percentage of land value.
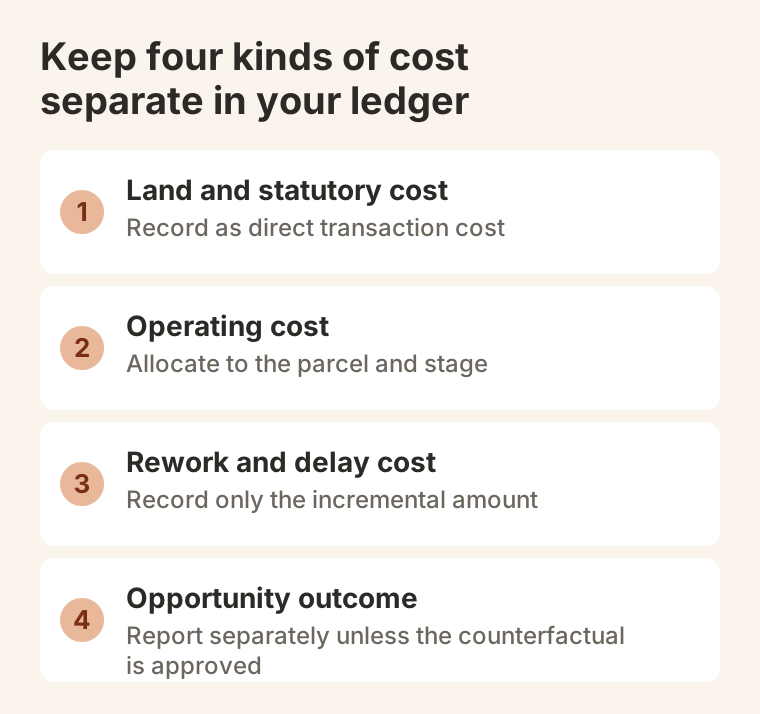
- Keep a ledger with one row per parcel and four cost classes apart.
- A guideline value, an asking price and a comparable registered transaction are different inputs. None of them alone proves that a buyer overpaid.
- A delay is a cash cost only when you can name an extra expense or an approved carrying-cost basis. A lost parcel is not lost profit.
- Software ROI should come from like-for-like before-and-after evidence, not a vendor benchmark.
Start with a cost ledger, not a savings claim
Use one row per parcel.
| Cost class | Examples | Evidence to retain | Treatment |
|---|---|---|---|
| Land and statutory transaction cost | Consideration, duties, registration fees | Executed instrument, portal calculation, payment record | Record as direct transaction cost |
| Operating cost | Staff time, travel, document retrieval, meetings | Time record, expense claim, task history | Allocate to the parcel and stage |
| Rework and delay cost | Repeated searches, corrected documents, extra legal work, incremental finance cost | Change log, invoice, dated dependency, finance input | Record only the incremental amount |
| Opportunity outcome | Parcel lost, price changed, approval expired | Dated offer history and documented reason | Report separately unless the counterfactual is approved |
For Tamil Nadu, a standard sale conveyance currently totals 9% in government charges on the applicable market value under TNREGINET’s valuation rules: 5% stamp duty, 2% transfer duty, and 2% registration fee. The official TNREGINET Duty and Fees schedule groups the first two components as 7% under its displayed “Stamp Duty” label. Other instruments and notified concessions have different rules; confirm the live schedule before execution.
Keep these charges in the total investment model, but out of any efficiency benchmark.
Define the unit and the clock before you count
Record, for every parcel:
- Entry event: for example, a lead accepted for desktop screening.
- Stage transitions: screening, document intake, legal review, commercial review, approval, offer, agreement, and registration.
- Exit event: registered, rejected, withdrawn by seller, lost to another buyer, or inactive.
- Exception status: title issue, survey mismatch, planning issue, seller delay, internal delay, or another documented cause.
- Cohort attributes: jurisdiction, intended use, parcel size, ownership complexity, and whether required approvals already existed.
Do not blend a clean single-owner plot and a multi-owner parcel into one “time to acquire”. Report comparable cohorts with their parcel counts. Medians and percentiles beat an average when a few exception-heavy parcels dominate.
Count staff time from records, not assumptions
Staff cost per parcel = sum of each person’s parcel hours × that person’s approved loaded hourly cost
Finance should supply the loaded hourly cost and apply it consistently. It may include salary and employer costs, but the model must say what it includes. Allocate meetings and messages only by a documented method.
Track by stage:
- time spent sourcing and screening;
- time spent collecting and reconciling documents;
- legal, finance, survey, and planning handoff time;
- internal approval wait time, recorded separately from active work; and
- repeated work caused by missing, incorrect, or superseded information.
This shows whether the problem is expensive activity, idle waiting, or both. A workflow tool may reduce either, but the evidence has to show which changed.
Count rework only when an earlier step had to be repeated
Rework means an earlier step was redone because its output was incomplete, incorrect, lost, or no longer current.
Rework cost = incremental external fees + incremental staff cost + attributable incremental carrying cost
Keep the cause next to the amount: a wrong survey subdivision in a search, an EC retrieved for an incomplete period, a survey comparison redone after the parcel description changed, or counsel’s review repeated after a missing deed arrived.
A genuine defect found in the original diligence step is not rework; finding it is what due diligence is for.
Separate real delay cost from exposure
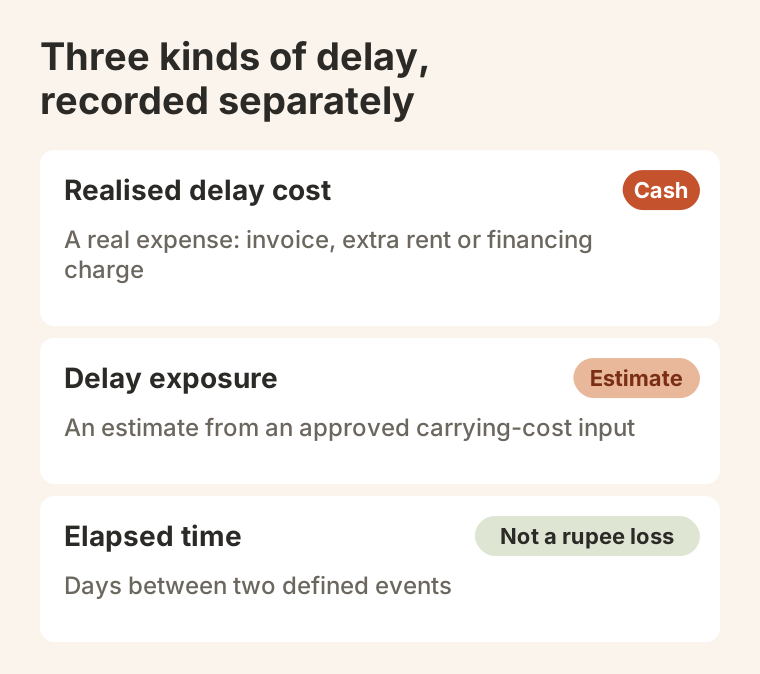
Delay means three different things. Record each on its own:
- Realised delay cost: an invoice, additional rent, extended financing charge, repeat visit, or other expense that occurred because a dated dependency slipped.
- Delay exposure: a scenario based on an approved daily or monthly carrying-cost input. Label it as an estimate and show the input.
- Elapsed time: calendar or business days between defined events. This is an operational measure, not itself a rupee loss.
Add a reason code such as “waiting for seller”, “waiting for counsel” or “waiting for internal approval”. A single total duration is not actionable.
Call a price gap a variance, not an overpayment
The difference between the agreed price and guideline value is not an overpayment calculation. Guideline value matters for registration and valuation rules, but a commercial valuation must rest on like-for-like evidence.
Before reporting a pricing variance, document:
- the exact village, survey context, and comparison date;
- whether the evidence is an asking price, registered transaction, valuation, or internal offer;
- land extent and the area denominator used;
- land use, approvals, access, frontage, shape, occupancy, and title condition; and
- adjustments made and who approved them.
Report the variance from the approved benchmark, and say “overpayment” only when your valuation method supports it after adjustments. The guideline-value checker compares a guideline rate you enter with a market rate you enter, but it does not establish open-market value by itself.
Record lost deals with a reason, and report only the spend as loss
Track each lost opportunity with evidence:
| Field | Example of acceptable evidence |
|---|---|
| Outcome | Seller withdrew, competitor completed, buyer rejected, approval expired |
| Decision point | Dated stage and last completed gate |
| Stated reason | Written seller response, approval record, or team decision note |
| Spend to date | Assigned staff cost and invoices already incurred |
| Counterfactual | Finance-approved model, if the organisation chooses to estimate profit impact |
Do not assume every parcel lost after screening would have closed or earned the target margin. The measurable loss is the spend already incurred; unrealised profit is a separate scenario.
Run a 30-day baseline audit
For one reporting cycle, collect data without setting “healthy” thresholds.
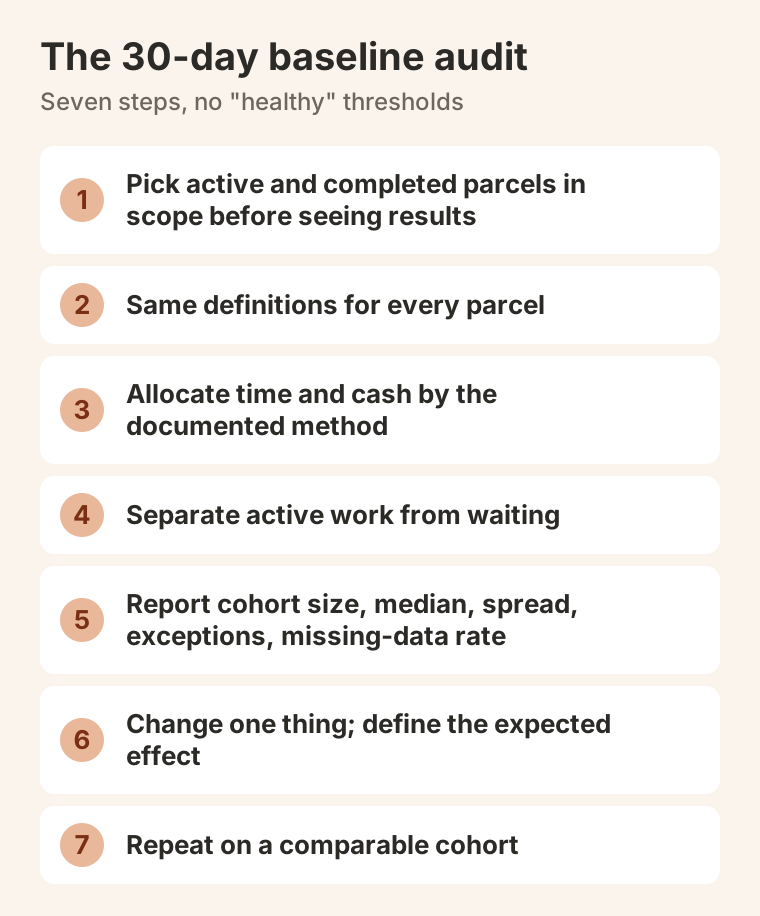
Missing data is a finding. If you cannot tell when a parcel entered legal review, which document caused a repeat search, or why an offer was delayed, build a reliable audit trail first.
Test a platform claim with the same measurement
Compare a manual process and a platform on the same measures:
| Question | Minimum evidence |
|---|---|
| Did staff time change? | Same activities, tracked hours, comparable parcel cohort |
| Did cycle time change? | Same entry and exit events, stage timestamps, exception mix |
| Did rework change? | Same rework definition and cause codes |
| Did cash cost change? | Invoices and finance-approved labour or carrying-cost inputs |
| Did the platform cause the change? | Deployment date, adoption evidence, and other material changes disclosed |
| Did the investment pay back? | Verified benefit less subscription, implementation, training, and operating cost |
A vendor savings percentage without the sample, period, cohort definition, exclusions and calculation is a marketing claim, not an input to the investment case.
What this means for you
If you run land acquisition for a developer: build the ledger and baseline before changing a process or buying a system, then judge each change on a comparable cohort.
If you are buying a single plot: keep a ledger of fees, travel and repeated work. Do not call the gap between your price and the guideline value an overpayment.
If you are selling land: an asking price, a guideline value and a registered transaction are different inputs. None of them alone proves that a buyer overpaid.
What this guide does not prove
This article does not establish an average hidden cost for Indian land acquisition, a normal level of overpayment, a standard deal duration, a parcel-count threshold for software, or a guaranteed ROI. It also does not value any parcel. Those conclusions require the organisation’s own operational records, parcel evidence, financial assumptions, and—where relevant—qualified legal and valuation advice.
Test whether software pays back for your team
Proquiro’s land acquisition management software can keep parcel stages and documents together, log changes to a lead, and, on the Pro plan and above, assign tasks. Test whether it pays back with the method above.
Sources and editorial notes
Methodology
This guide defines a first-party measurement method. It uses parcel-level timestamps, time records, invoices, approved finance inputs, and documented outcomes; it does not use an industry-average cost or claim product savings.
Sources
- TNREGINET Duty and Fees schedule — Tamil Nadu Registration Department (TNREGINET)Primary source · Checked Used only for the current Tamil Nadu standard-conveyance charge example; operational costs must come from the reader’s own records.
Updates and corrections
- Removed unsupported cost, time, overpayment, rework, deal-loss, capacity, savings, and ROI benchmarks; replaced them with auditable formulas and limitations.
Questions
Measure your manual workflow before changing it
Model your team size, parcel volume, coordination time, and software cost.
Continue reading
Site visit vs desk due diligence for Tamil Nadu land
What a records check and a field visit each catch on Tamil Nadu land, where they disagree, and how land teams sequence and log both before an advance.
Sale Deed vs. Agreement to Sell: What a Land Buyer Really Gets
What an agreement to sell and a sale deed each secure, Tamil Nadu registration rules, EC searches, mutation, and your options if the seller defaults.
WhatsApp for Land Deals: Define Its Role
What a land team can keep in WhatsApp, and which parcel decisions, files and approvals must be copied into the parcel record.