Stamp Duty and Registration Charges in Tamil Nadu: 2026 Guide
Tamil Nadu stamp duty and registration charges by document type: sale deeds, gifts, settlements, partitions, mortgages and first sales, with worked examples.
Vignesh Nagarajan · · Updated · 10 min read · Source: Tamil Nadu Registration Department (TNREGINET)
On this page
This guide is for developers’ land teams, single-plot buyers and families transferring land in Tamil Nadu. It covers Tamil Nadu only, and it follows the Registration Department’s TNREGINET Duty and Fees schedule. State notifications can change rates and concessions, so use the schedule and the portal’s live calculation before execution.
In short
- A standard sale deed costs a 9% total: 5% stamp duty + 2% transfer duty + 2% registration fee, on the market value accepted for registration.
- On a ₹10 crore applicable market value that is ₹90 lakh. The cost does not shrink because the parcel is large.
- Every deed is charged on its own. A site of 40 separately owned parcels usually means 40 instruments, not one registration charge.
- The document type sets the rate. A gift deed has no family discount; only qualifying family settlements, partitions and releases get the ₹40,000 and ₹10,000 caps.
- The women-buyer concession takes one percentage point off the registration fee, only at ₹10 lakh or less.
Budget 9% on a sale deed, not 7%
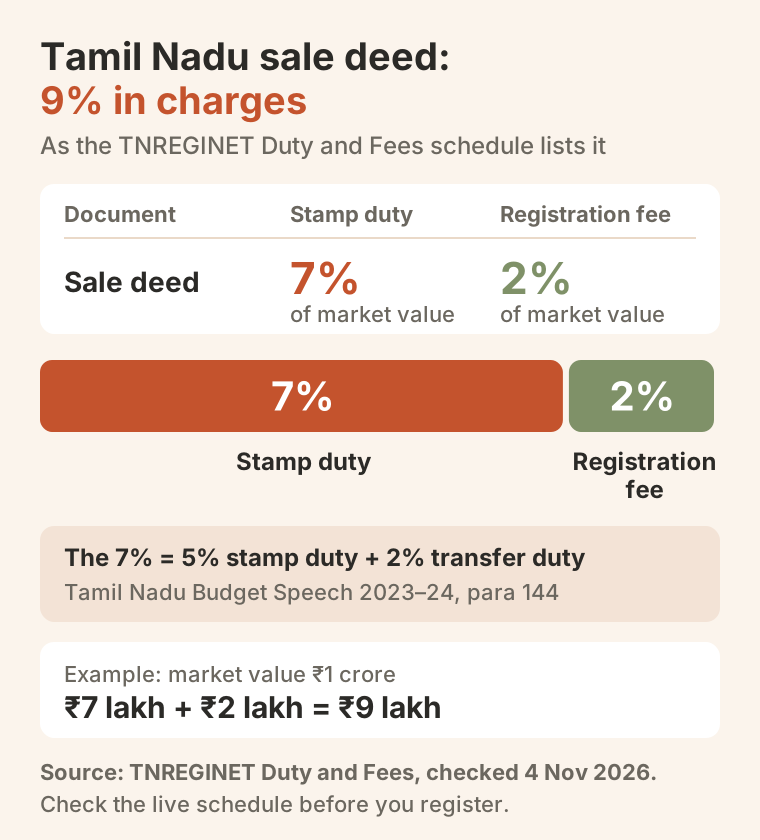
A standard conveyance or resale sale deed attracts a 9% total: 5% stamp duty + 2% transfer duty + 2% registration fee. These components apply to the applicable market value under TNREGINET’s valuation rules.
TNREGINET’s current Duty and Fees table displays the 5% stamp-duty and 2% transfer-duty components together as 7% under “Stamp Duty”, with the 2% registration fee shown separately. That portal label is an aggregate display, not the full statutory decomposition. There is no general registration-fee cap for a standard sale deed.
Find the market value before you make an offer
Use the Tamil Nadu guideline value lookup before issuing an offer or LOI. The applicable value depends on the property description and Sub-Registrar Office jurisdiction published through TNREGINET. A district-wide average is not an adequate substitute.
Do not substitute either the negotiated price or the guideline value automatically. Confirm the market value accepted for registration through the live TNREGINET process. The Tamil Nadu stamp duty calculator applies the rate and caps for the document type you select to the value you enter.
Sale-deed charges at ₹30 lakh, ₹1 crore and ₹10 crore
| Applicable market value | Stamp duty (5%) | Transfer duty (2%) | Registration fee (2%) | Total charges (9%) |
|---|---|---|---|---|
| ₹30 lakh | ₹1,50,000 | ₹60,000 | ₹60,000 | ₹2,70,000 |
| ₹1 crore | ₹5,00,000 | ₹2,00,000 | ₹2,00,000 | ₹9,00,000 |
| ₹10 crore | ₹50,00,000 | ₹20,00,000 | ₹20,00,000 | ₹90,00,000 |
Example: if TNREGINET’s valuation process establishes an applicable market value of ₹82 lakh, the charges are ₹4.10 lakh of stamp duty, ₹1.64 lakh of transfer duty and ₹1.64 lakh of registration fees, or ₹7.38 lakh in total.
Use the rate for the document you are signing
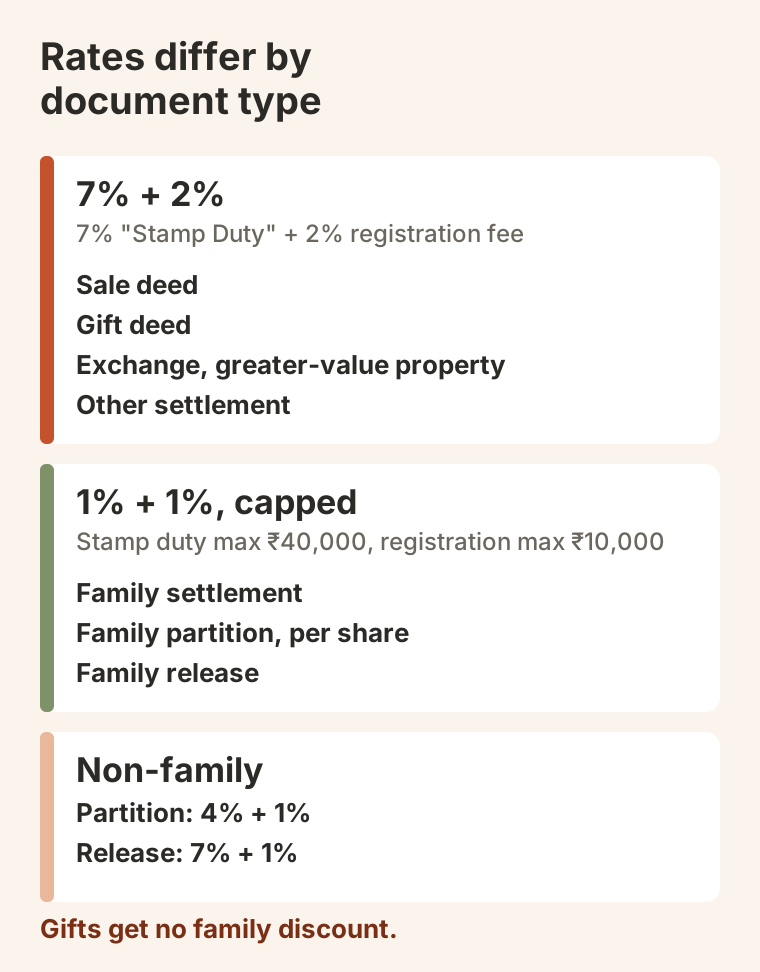
Using the sale-deed rate for every document is a common and expensive modeling error. Tamil Nadu applies different rates and caps to gifts, settlements, partitions, releases, mortgages, construction agreements and powers of attorney.
| Instrument | TNREGINET “Stamp Duty” display | Registration fee |
|---|---|---|
| Sale deed (conveyance/resale) | 7% (5% stamp + 2% transfer duty) | 2% |
| Exchange, on the greater-value property | 7% | 2% |
| Gift deed | 7% | 2% |
| Construction agreement | 1% of contract amount | 3% of contract amount |
| Simple mortgage without possession | 1%, max ₹50,000 | 1%, max ₹15,000 |
| Mortgage with possession | 4% | 1%, max ₹2,00,000 |
| Family settlement | 1%, max ₹40,000 | 1%, max ₹10,000 |
| Other settlement | 7% | 2% |
| Family partition, per share | 1%, max ₹40,000 per share | 1%, max ₹10,000 per share |
| Non-family partition | 4% | 1% |
| Family release | 1%, max ₹40,000 | 1%, max ₹10,000 |
| Non-family release | 7% | 1% |
| General PoA to sell, non-family | 1% | 1% |
| General PoA given for consideration | 5% | 1% |
For a construction agreement, the base is the contract amount or the amount stated in the document, if higher.
The schedule’s definition of “family” controls whether a concessional settlement, partition or release rate applies. Confirm that every party falls within the statutory relationship definition before using the capped rate.
Gifts get no family discount
The current TNREGINET schedule lists a gift deed at 7% under its displayed “Stamp Duty” column and 2% registration. It does not split gifts into family and non-family rates. The lower family rates belong to specified settlements, partitions and releases. Treating a family gift as a 3% or 5% transaction understates the payable amount.
Family caps apply to settlements, partitions and releases
For a qualifying family settlement or release, the 1% stamp-duty component is capped at ₹40,000 and the 1% registration component at ₹10,000. A qualifying family partition uses the same caps per share. Non-family instruments use different rates and generally do not receive those family caps.
Example: a qualifying family settlement valued at ₹80 lakh reaches both caps.
| Component | Percentage result | Amount payable after cap |
|---|---|---|
| Stamp duty at 1% | ₹80,000 | ₹40,000 |
| Registration fee at 1% | ₹80,000 | ₹10,000 |
| Total | ₹1,60,000 before caps | ₹50,000 |
Check the slab for a first-sale home
G.O. Ms. No. 131, Commercial Taxes and Registration, dated 1 December 2023 cuts the stamp duty on the first sale of an apartment, flat, villa, row house or villament in a real estate project. The duty is charged on the composite value of the undivided share of land and the building: the value in the deed or the composite value fixed by the authority on super built-up area, whichever is higher.
| Composite value | Stamp duty (G.O. 131) | With transfer duty | Registration fee | Combined rate |
|---|---|---|---|---|
| Below ₹50 lakh | 2.86% | 4% | 2% | 6% |
| ₹50 lakh to ₹3 crore | 3.575% | 5% | 2% | 7% |
| Above ₹3 crore | 5% (no cut) | 7% | 2% | 9% |
The G.O. sets only the stamp duty part. Added to transfer duty, the way TNREGINET shows a sale under “Stamp Duty”, it comes to 4% and 5%. A home valued at exactly ₹50 lakh falls in the second band. Confirm the figures for your deed on TNREGINET before you register.
The cut applies only to the first sale of the undivided share with the home in a real estate project. Do not apply it to a resale, an open land purchase or an unrelated instrument; those follow their own schedule entries.
Claim the women-buyer concession only if every condition holds
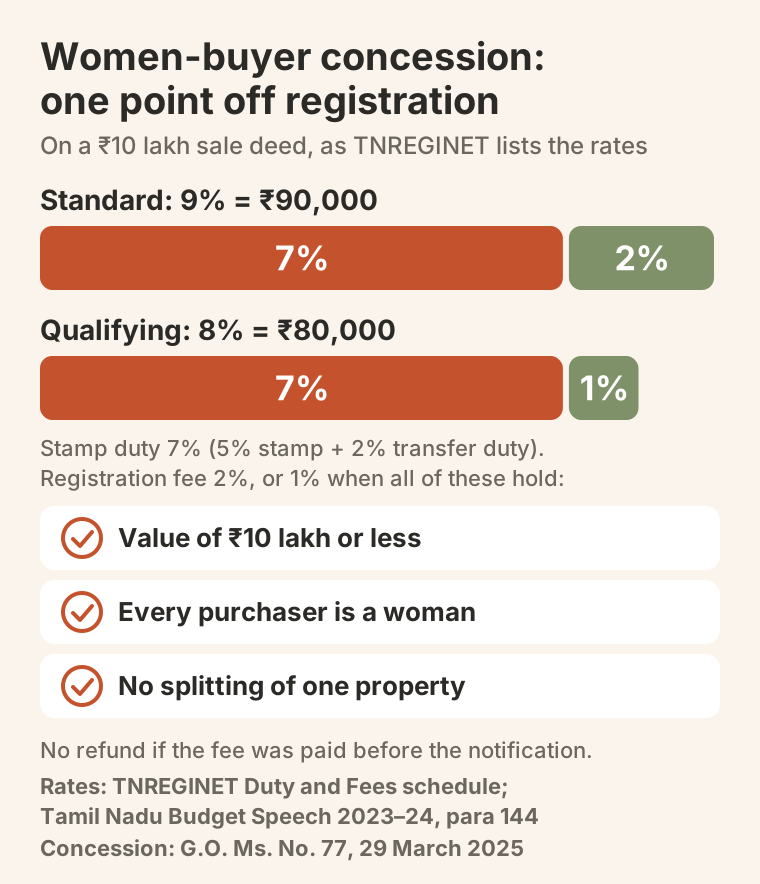
Tamil Nadu’s G.O. Ms. No. 77, Commercial Taxes and Registration, dated 29 March 2025 reduces the registration fee by one percentage point for a qualifying conveyance on sale of immovable property. The concession is narrower than many summaries suggest:
- the value must be ₹10 lakh or less under the market value or guideline rate prevailing when the document is presented;
- the purchaser must be a woman, or every purchaser must be a woman in a joint purchase;
- the concession does not apply at all when the property value exceeds ₹10 lakh;
- one property cannot be deliberately split into smaller parts to claim the concession; and
- the notification does not provide a refund where the registration fee was already paid before publication.
The concession changes only the registration-fee component. It does not reduce the 5% stamp-duty or 2% transfer-duty components.
For a qualifying women-buyer conveyance, the working rate is therefore 5% stamp duty + 2% transfer duty + 1% registration fee, or 8% total. On an applicable value of ₹10 lakh, that is ₹80,000 instead of the standard ₹90,000. Above ₹10 lakh, the standard schedule applies rather than a partial concession.
A rate table you saved earlier may be out of date, because a notification can change the schedule. Confirm the instrument, ownership structure and value on TNREGINET immediately before presentation. If any condition is uncertain, budget the standard rate and treat the concession as a potential saving rather than an approved base-case assumption.
Price every deed separately in a multi-parcel acquisition
Build the calculation at deed level, not project level. Family partitions use per-share caps, and an assembly of parcels means many deeds. The land acquisition cost calculator can combine the stamp duty and registration rates you enter with brokerage, legal fees and other acquisition costs. Keep its document-level assumptions attached to the deal record so reviewers can reproduce the number.
Before a final cost is approved:
- Confirm the exact instrument and every required supporting instrument.
- Identify the correct SRO, the office with jurisdiction over the property, which determines the applicable guideline-value record, and retrieve the current valuation inputs.
- Determine the applicable market value under TNREGINET’s valuation rules.
- Calculate stamp duty, transfer duty and registration fees separately. Caps may apply to one component but not the other.
- Apply only the caps and concessions supported by the instrument and parties.
- Keep a separate row for every registrable instrument or share.
- Recheck the live TNREGINET Duty and Fees schedule.
- Save the rate source and calculation with the transaction record.
What this means for you
A developer’s land team: Model charges per deed, never per project. Budget the standard rate for every parcel, repeat the calculation for each instrument, and save the TNREGINET schedule you used with each deal record.
A single-plot buyer: Budget 9% on the market value accepted for registration, and do not assume the negotiated price or the guideline value is that figure. Treat the women-buyer concession as a possible saving, and count on it only if the value is ₹10 lakh or less and every purchaser is a woman.
A family or owner transferring land: Check which instrument you are actually signing. A gift has no family discount, and the family caps apply only to qualifying settlements, partitions and releases where every party meets the schedule’s definition of family.
Sources and editorial notes
Methodology
Rates were checked against the live TNREGINET schedule; the women-purchaser concession was checked against the official Gazette notification.
Sources
- TNREGINET Duty and Fees schedule — Tamil Nadu Registration Department (TNREGINET)Primary source · Checked Live department schedule used for current instrument rates and fee caps.
- G.O. Ms. No. 77 — reduction of registration fee for qualifying women purchasers — Tamil Nadu Stationery and Printing DepartmentPrimary source · Checked Official notification published on 29 March 2025; defines the one-percentage-point concession and its conditions.
Updates and corrections
- Replaced the vague women-buyer concession wording with the official rate, ₹10 lakh threshold, women-only ownership condition, and anti-splitting rule.
Questions
Estimate Tamil Nadu stamp duty and fees
Apply the reviewed rates to the selected document and transaction assumptions.
Continue reading
G.O. 194 explained: 19.50m replaces 18.30m in listed building rules
HUD G.O.(Ms) No. 194 of 26 October 2026 replaces 18.30m with 19.50m in listed TNCDBR rules and amends others, including zoning, road width, parking and pools.
A-Register in Tamil Nadu: How to Read It Before You Buy Land
How to view and read Tamil Nadu's A-Register on TN eServices, what its 16 fields mean for due diligence, and which entries should stop a land deal.
Agricultural Land Conversion in Tamil Nadu: Which Route Applies
Which Tamil Nadu land-conversion route applies to a parcel: non-planning area rules, planning-area reclassification, charges, documents and coastal limits.